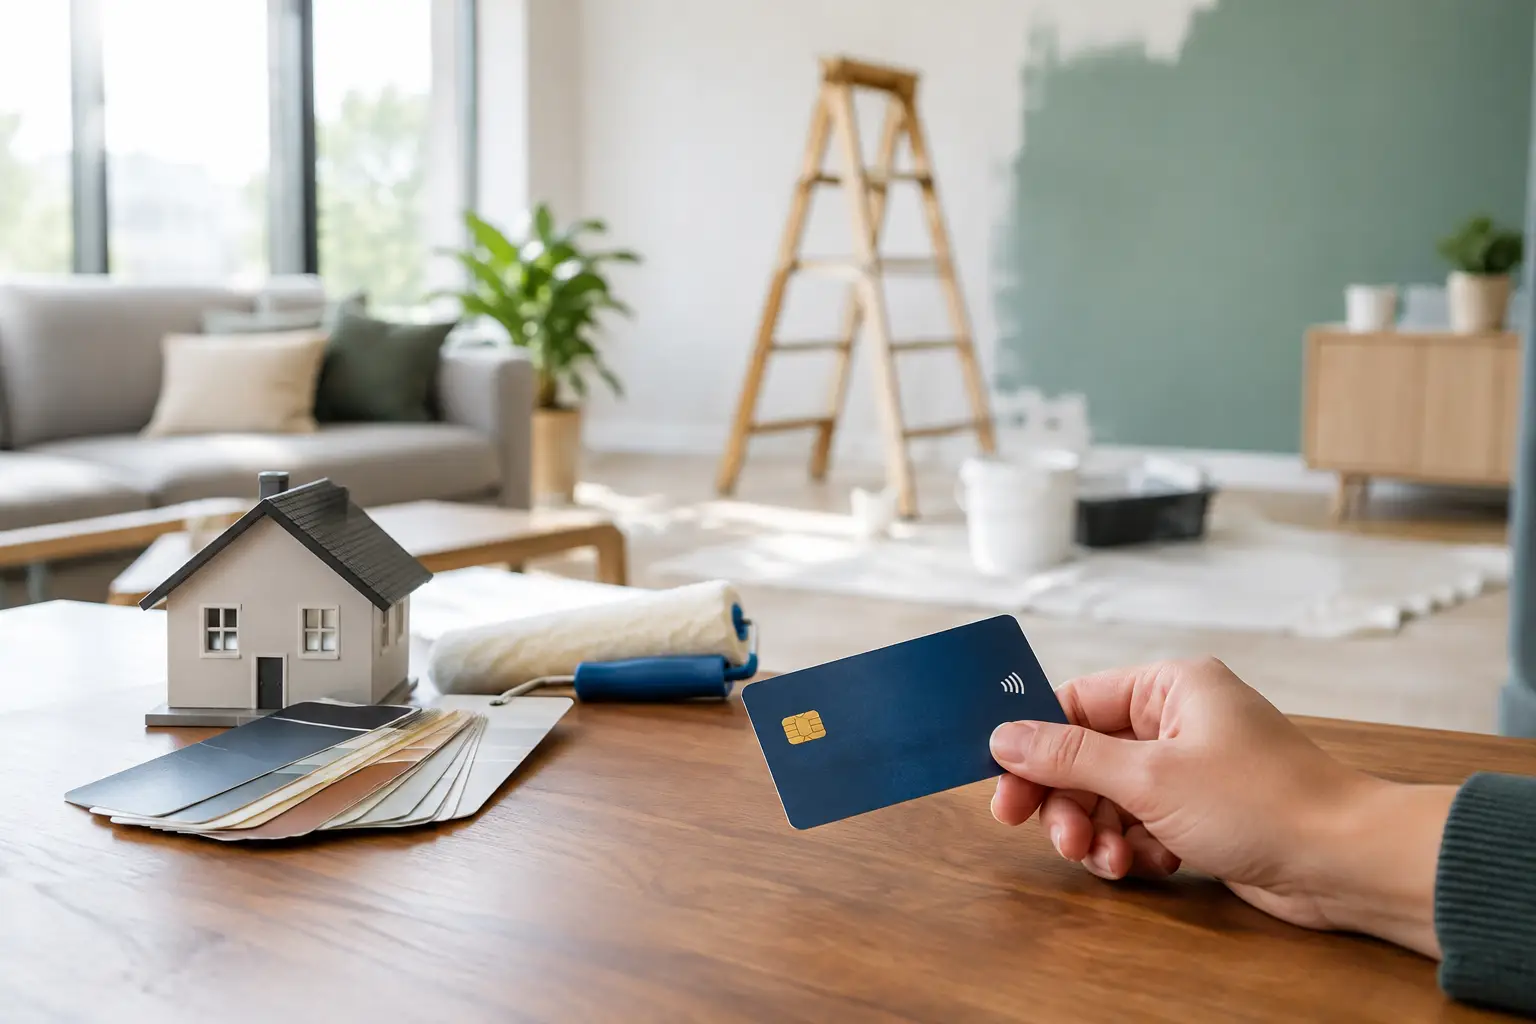
A renovation rarely arrives as one neat, predictable invoice. There is the design concept, site preparation, custom joinery, finishes, appliances, lighting, and the small decisions that turn a room into a living work of art. Interior renovation by credit card can offer welcome flexibility when used with a clear plan. Used without one, it can make a beautiful project significantly more expensive than it needs to be.
For homeowners and business owners, the question is not simply whether a card can pay for renovation work. It is whether that payment method supports the scope, timeline, and financial comfort of the project. The right answer depends on the cost of the work, your card terms, the contractor’s payment schedule, and how quickly you can repay the balance.
When Interior Renovation by Credit Card Makes Sense
A credit card can be a sensible payment tool for a defined portion of a renovation, especially when the expense is planned and repayment is already accounted for. It may work well for a kitchen appliance package, lighting selections, hardware, furniture deposits, or a small refresh where the full balance can be paid before interest applies.
Cards can also add a layer of transaction visibility. A clear statement helps clients track purchases against their approved design budget, which is useful when several finish selections or suppliers are involved. Depending on the card and provider, rewards or purchase protections may add value too. These benefits should be treated as a bonus, not the reason to take on a balance.
For a larger villa renovation, apartment fit-out, or commercial interior project, a card is usually best used selectively. Major works involve staged payments, coordination across trades, material lead times, and contingency planning. Financing the entire project on a high-interest revolving balance can place unnecessary pressure on decisions that should be guided by design quality, technical requirements, and long-term value.
Start With the Project Budget, Not the Card Limit
A card limit is not a renovation budget. The budget should be established during the planning stage, after the scope has been defined and priorities have been agreed upon. It needs to cover design, construction, materials, joinery, approvals where applicable, furniture or equipment, and a realistic contingency for changes discovered once work begins.
A polished interior is built through hundreds of connected details. If the budget only covers the visible finishes, clients can find themselves compromising later on elements that affect how the space performs, such as storage layouts, electrical upgrades, ventilation, waterproofing, or durable hardware.
Before deciding to charge any amount, separate the project into three categories: essential works, high-value upgrades, and optional enhancements. Essential works may include repairs or technical upgrades that protect the property. High-value upgrades might include bespoke cabinetry that improves daily function and supports the home’s overall character. Optional enhancements are the features that can be postponed without disrupting the completed space.
This approach creates room to make informed choices. If a desired finish would push the card balance beyond a comfortable repayment amount, it may be better to adjust the specification than to stretch the financial plan.
Know the True Cost of Carrying a Balance
Credit cards are convenient, but convenience has a price when a balance remains after the interest-free period. Review the annual percentage rate, promotional period, late-payment terms, foreign transaction fees if materials are being purchased internationally, and any contractor surcharge for card payments.
A seemingly manageable balance can grow quickly when only minimum payments are made. That matters even more on a renovation because the project may continue to generate costs after the first charge appears. A custom joinery deposit today could be followed by installation, accessories, and final styling purchases weeks later.
A simple test is helpful: calculate the monthly payment required to clear the renovation balance within the promotional period or within a timeframe you are genuinely comfortable with. If that payment would disrupt savings, operating cash flow, rent, mortgage obligations, or other priorities, reduce the amount placed on the card.
Match Payments to the Renovation Schedule
Well-managed renovation projects follow clear stages: initial consultation, design and planning, implementation, and final handover. Your payment strategy should follow the same logic.
During design and planning, invest in decisions that prevent costly revisions later. Detailed space planning, material selections, technical drawings, and a coordinated scope give you a firmer view of what the project will require. This is the moment to decide which elements, if any, are appropriate for credit-card payment.
During implementation, avoid treating every new idea as an impulse purchase. A change to a finish, layout, or joinery detail can affect more than one trade. Ask for the cost and schedule implications before approving it. A refined home or workplace should feel effortless at handover, but the route to that result depends on disciplined coordination behind the scenes.
At final handover, inspect the completed work against the approved scope. Keep invoices, payment confirmations, warranties, and material records organized. This protects both the investment and the future value of the property.
Choose a Contractor Who Makes Costs Visible
The biggest financial risk in renovation is not always the payment method. It is an unclear scope. Vague quotations, incomplete specifications, and fragmented contractor responsibility can create variations that no card rewards program will offset.
Look for a design-and-build partner that can connect creative direction with technical execution. You should understand what is included, what may be excluded, the payment stages, and the approval process for changes. Transparent pricing is not about making every decision cheap. It is about making each decision visible before it becomes a surprise.
An integrated team can be especially valuable when the project includes design, fit-out, bespoke joinery, and multiple trades. Instead of managing separate designers, installers, carpenters, and suppliers yourself, you have a clearer line of accountability from first concept to final handover. Aakruti Technical Services Co. approaches projects this way, pairing tailored design with hands-on project coordination and quality-focused delivery.
For clients considering a Renovate Now, Pay Later option, compare its terms with those of a credit card rather than assuming one is automatically better. A structured financing arrangement may offer more predictable payments for a larger scope. A card may offer greater flexibility for a smaller, short-term purchase. The best choice is the one that keeps the payment schedule aligned with your actual cash flow.
Four Questions to Ask Before You Pay by Card
Before charging renovation costs, pause long enough to answer four practical questions:
- Can I repay this amount in full before interest, or within a defined period without financial strain?
- Does this payment cover an approved item in the project scope, rather than an unplanned addition?
- Have I confirmed whether the contractor charges a card-processing fee?
- Will this purchase leave adequate contingency for genuine project changes?
If the answer to any of these is no, it does not mean the renovation should stop. It may mean the payment structure needs to change. A staged plan, revised material selection, or financing option designed for renovation can protect the project from becoming a source of stress.
Keep the Design Ambitious and the Spending Intentional
The goal of a renovation is not to spend as little as possible. It is to spend purposefully on a space that works beautifully, reflects your taste, and performs for years. In a home, that may mean investing in durable kitchen joinery and simplifying decorative extras. In an office or customer-facing space, it may mean prioritizing circulation, lighting, brand presence, and finishes that stand up to daily use.
Credit can support that vision when it is a planned tool, not a substitute for planning. Use it for costs you understand, within a scope you have approved, and with a repayment path that feels controlled from the start. That gives the design room to shine while keeping the financial side of the project just as carefully crafted.